Income Generating Assets: Types, Risks and Comparison
Fragmenta Books Team · Published on Oct 23, 2026
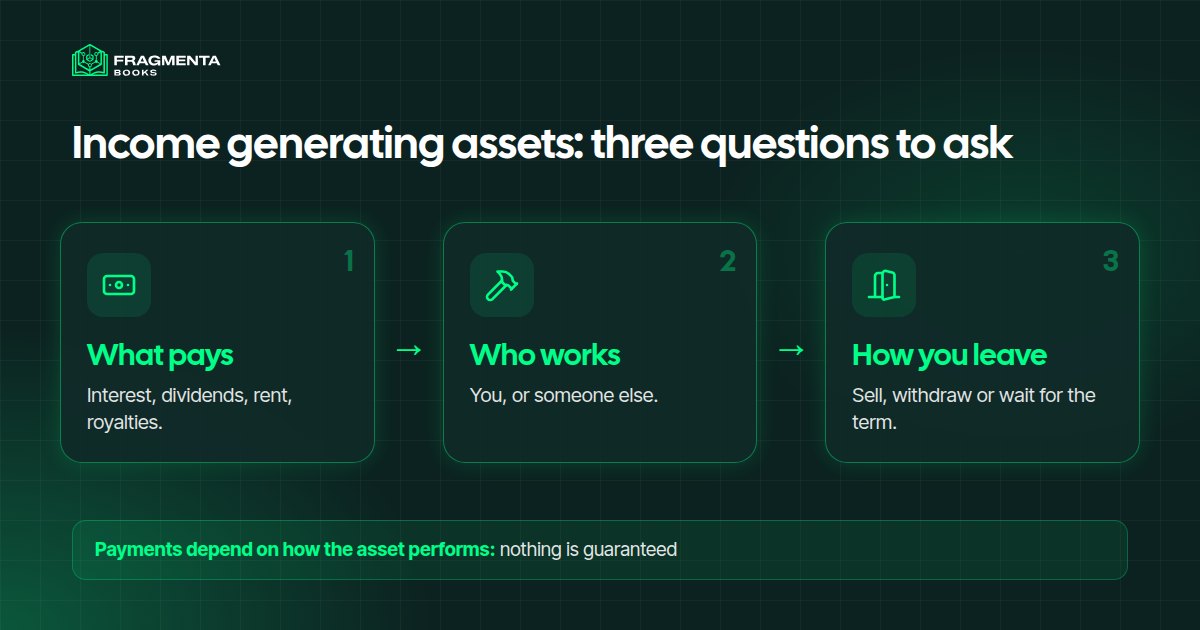
Income generating assets are things you own, or hold a right to, that pay you money on a regular basis: interest on a deposit, dividends from shares, rent from a property, royalties from a creative work, or a share in what a business earns. They differ in how much money they need, how much work they leave to you, how risky they are and how easily you can leave. None of them pays a guaranteed amount, and what you receive always depends on how the underlying asset actually performs.
In short
- An income generating asset pays you from something it produces (interest, dividends, rent, royalties), not only from a rise in its price.
- The main types are deposits, bonds, dividend shares and funds, rental property, royalties, small businesses, and participations in assets run by others.
- Compare them on five points: what you put in, what pays you, how much work is left, what can go wrong, and how you leave.
- Higher possible payments come with a higher chance of loss. The FCA warns that high-risk products can lose all of the money put in.
- A share in the royalties of books is one option among these. Payments depend on how the books actually sell.
What is an income generating asset?
An asset is anything of value that you own or have a right to. It becomes an income generating asset when it produces a cash flow, a movement of money towards you, on top of whatever it is worth if you sold it. Businesses use the same idea: their cash flow is what is left when the money going out is subtracted from the money coming in.
For a person the question is the same and simple: what pays me, how often, and what does it cost me to keep it paying? A flat you rent out pays rent but costs repairs. A share pays a dividend if the company decides to. A book pays royalties as long as readers keep buying it.
There is also a difference to keep in mind between income and price. A painting or a plot of land may go up in value without paying you anything while you hold it. An income generating asset pays along the way, which is why people look at it when they search for a steadier second source of money. Passive income is usually defined as income acquired with little to no labor to earn or maintain, and the word "little" matters: almost every asset needs money, time or attention somewhere.
The main types of income generating assets
1. Savings accounts and term deposits
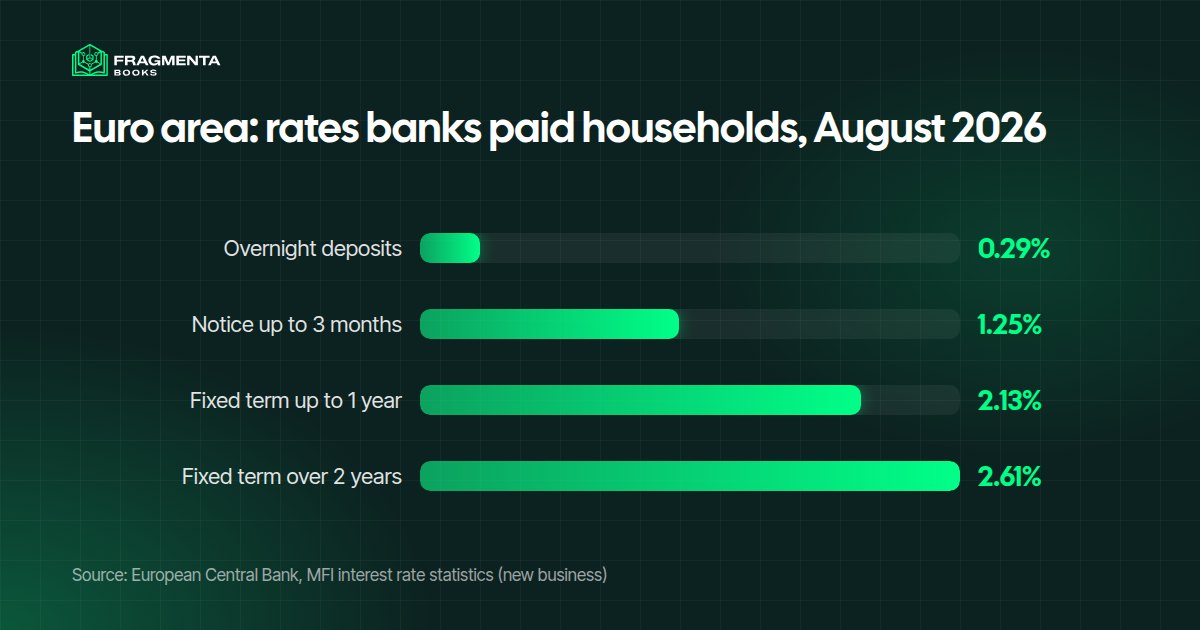
You lend money to a bank and it pays interest. There is almost nothing to do and the risk is low, but the payment follows the central bank's rate. The Bank of England's Bank Rate is currently 3.75%, and the European Central Bank's deposit facility rate is 2.50% (Bank of England, ECB). What a bank pays you is usually below those figures, and the rates change.
The ECB's bank interest rate statistics show the gap. In August 2026, euro area banks paid households 0.29% on overnight deposits, 1.25% on savings with up to three months' notice, 2.13% on fixed-term deposits of up to one year and 2.61% on fixed-term deposits of over two years, for new deposits (ECB, MFI interest rate statistics).
2. Bonds
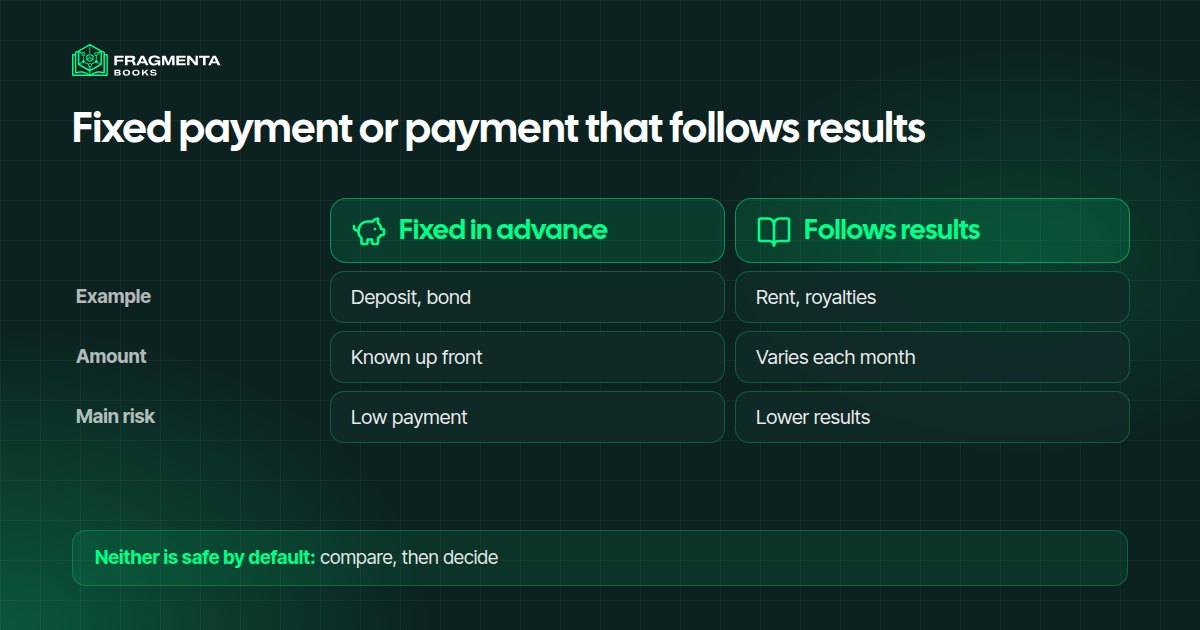
A bond is a loan to a government or a company that pays a fixed interest. It is steadier than shares in normal times, but the issuer can fail to pay and the price you would get by selling early can fall.
3. Dividend shares and funds
Some companies share part of their profit with shareholders. Once you have chosen what to hold, the effort is low. But prices move every day and a dividend can be cut. In the UK there is a dividend allowance of £500 a year before dividend tax applies (GOV.UK).
4. Rental property
Rent is the classic income generating asset. You need a large amount up front and then deal with repairs, tenants, empty periods and taxes, or pay an agent to do so. Even a small version comes with rules: under the Rent a Room Scheme you may earn up to £7,500 a year tax-free from a furnished room in your home (GOV.UK).
5. Royalties from creative work
A book, a song or a piece of software can keep earning after it is finished. Amazon KDP, for example, lets authors choose between a 35% and a 70% royalty option on eBooks (Amazon KDP Help). The work comes first, and many titles earn little. We look at the numbers in how much authors make per book and at the buying side in investing in royalties.
6. A small business or website
An online business that already earns can be bought, but then you own all the work and the risks of running it. Read how to buy an online business before you consider it.
7. Participations and loans run by others
Property crowdfunding, peer-to-peer loans and similar offers give you a contractual right to a part of what a project or a borrower pays, while someone else does the work. The entry amount is often low, but projects can fail and leaving early is not always possible. See real estate crowdfunding and peer-to-peer lending.
The types compared
| Money needed | Work left | What pays you | Main risk | How you leave | |
|---|---|---|---|---|---|
| Deposits | Any amount | Almost none | Interest | Low payment, inflation | Withdraw, or end of term |
| Bonds | Moderate | Low | Fixed interest | Issuer fails to pay | Sell, or end of term |
| Dividend shares and funds | Any amount | Low | Dividends | Prices fall, dividends cut | Sell, usually quickly |
| Rental property | High | Medium to high | Rent | Empty periods, repairs | Sell the property, slowly |
| Royalties from your own work | Your time | High at the start | Royalties | Few sales | Keep it, or sell the rights |
| Small business or website | Moderate to high | Medium to high | What the business earns | Overpaying, traffic drops | Sell it to a buyer |
| Participations run by others | Low to moderate | Low | A share of what the asset earns | The asset earns less | Depends on the offer |
Advantages and limits
Advantages
- A second source of money. Payments that do not depend on your working hours give you more than one source of income.
- Different shapes for different budgets. There is an option from a savings account to a rented flat.
- You can see what pays you. With an asset that has records, you can read the payments of past months before you decide.
Limits
- Never guaranteed. The FCA says high-risk products may offer the chance of higher returns but put your money at higher risk, and that you could lose all of it (FCA).
- Not effortless. Even the calmest option asks for money, time or attention somewhere.
- Costs and taxes. Fees, platform charges and tax can take a large part of what you receive.
- Payments move. Interest follows central banks, dividends follow results, royalties follow sales.
- Getting out can be slow. A flat or a loan with a term cannot always be turned back into cash quickly.
What we see in our own catalogues makes the last two points concrete: royalties do not arrive as a flat line. They move from month to month in the Amazon KDP reports, and they come from many titles in several languages, not from one bestseller. An income that looks regular over a year is usually the sum of many small and uneven ones.
How to compare income generating assets, step by step
- Write down what you put in: money, time, or both, and for how long.
- Find out what pays you and what must happen for the payment to arrive.
- Ask who does the work. If it is you, count the hours. If it is someone else, ask what they earn if it goes badly.
- Read the track record, including the bad months, not only the average.
- Check the costs and the tax on what you receive.
- Find the exit before you enter: how long, at what cost, and what if nobody wants to buy.
- Spread the amount across more than one asset instead of relying on one.
This video, from a CFA charterholder, explains why most income ideas need a lot of capital or work up front and why promises of effortless money deserve caution.

Where a book royalty participation fits
A participation in book royalties belongs to the seventh type: you hold a contractual right to a share of an asset that someone else manages. The table puts it next to two other options. None is better in general.
| Rental property | Writing and publishing your own book | Participating in a book collection at Fragmenta Books | |
|---|---|---|---|
| What the money is linked to | One property | Your own book | The net royalties of a collection of books on Amazon KDP |
| What you hold | The property | The book and its rights | A contractual right to a share of the net royalties, recorded as tokens |
| Who does the work | You, or an agent you pay | You, before and after publishing | The founder, who keeps at least 51% and manages the books |
| Amount needed | A deposit and costs | Your time and some costs | Units you choose |
| How you leave | Sell the property | Keep it or sell the rights | Offer your units to other members through secondary transfers |
| Main risks | Empty periods, repairs, price falls | Few sales | Book sales can fall; transfers depend on other members |
Payments in every column depend on how the underlying asset actually performs. None of them is guaranteed.
How it works at Fragmenta Books
Fragmenta Books groups books published on Amazon KDP into collections and opens up to 49% of their net royalties to participants; the founder keeps at least 51% and goes on managing the books. Every participation is divided into units, recorded as tokens on the Base blockchain, and royalty distributions arrive every three months in USDC, straight to the participant's wallet. Every participation also includes the digital copies of the books in the collection.
Before you take part you can read the numbers: each collection page publishes the monthly royalty records, with the original KDP reports attached. Past royalties do not say what future ones will be. A participant who wants to leave can offer their units to other verified members through secondary transfers; the rights pass to the new holder with an Assignment & Novation Agreement. To see how collections are chosen, read the evaluation process.
How to take part in a book collection, step by step
- Choose a collection among the open book collections and the number of units.
- Create your account and add your residence details.
- Verify your identity (KYC) with a document and a selfie, directly on the site.
- Connect a wallet, or create one in a few clicks.
- Sign the Licensing Participation Agreement online.
- Pay by card or bank transfer. Once the payment is confirmed, the tokens are sent to your wallet.
Checklist: what to check before choosing an income generating asset
- What do I put in, and for how long can I leave it untouched?
- What exactly pays me, and when does the first payment realistically arrive?
- Who does the work, and what happens if they stop?
- What are the costs and taxes on what I receive?
- How do I get out, and how long could it take?
- Do I have the records of past payments, including the weak months?
- Is the promise too good to be true? A steady high payment with no risk does not exist.
- Is it only one asset? Spreading across several lowers the weight of any single failure.
Who it is for
Income generating assets suit anyone who wants a second source of money beside a salary, as long as the asset matches the money, time and patience they actually have.
- An employee with savings and little free time: chooses deposits, bonds or dividend funds, where almost no work is left, and accepts payments that follow interest rates and company decisions.
- Someone ten years from retirement: builds a mix of assets that pay along the way, so that regular payments can later sit beside a pension, and favours those that can be turned back into cash without a long wait.
- A person with a large sum and time to manage: buys a flat to rent out and deals with tenants, repairs and taxes, or pays an agent, for rent tied to a real building.
- Someone with skills more than capital: creates a book, a course or a piece of software that earns royalties, putting the hours in first and knowing the payments can take months to arrive.
Key terms
- Cash flow: the money that actually reaches you from an asset, once what goes out has been subtracted from what comes in.
- Term deposit: money left with a bank for a fixed period at an agreed rate, usually higher than on an account you can empty at any time.
- Dividend: the part of a company's profit paid out to its shareholders, which the company can cut.
- Bond: a loan to a government or a company that pays a fixed interest until it is repaid.
- Royalty: a payment to the owner of a work, such as a book or a song, for each sale or use of it.
- Liquidity: how quickly, and at what cost, an asset can be turned back into cash.
Frequently asked questions
What are income generating assets?
They are assets that pay you money on a regular basis, such as interest, dividends, rent or royalties, and not only through a rise in their price. Deposits, bonds, dividend shares, rental property and royalty rights are all examples.
What is the safest income generating asset?
Deposits and government bonds are usually considered the steadiest, and they also pay the least. No asset is risk-free: the safest in one respect, such as losing capital, may lose in another, such as keeping up with rising prices.
Do income generating assets need a lot of money?
It depends on the type. A savings account can start with any amount, a rented property needs a deposit and costs, and a participation in an asset run by others can start with units you choose. The right amount is one you could afford to lose and not need back soon.
Is rental property better than royalties?
Neither is better in general. Rent comes from one property and asks for upkeep or an agent; royalties come from a creative work and depend on sales. The comparison table above shows what each one needs and risks.
Can you lose money with income generating assets?
Yes. The FCA warns that higher-risk products can lose all the money put in, and even a deposit can lose purchasing power if prices rise faster than the interest.
Who does the work in a book royalty participation?
The founder manages the books, so the participant does not run them. It is still a participation, not a promise: royalty distributions depend on how the books actually sell, and secondary transfers depend on other members.
Sources
- Wikipedia, Cash flow: money coming in and going out, and why the difference matters.
- Wikipedia, Passive income: the definition of income acquired with little to no labor.
- ECB, MFI interest rate statistics: the rates euro area banks pay households on new deposits, by type and maturity.
- Bank of England, Interest rates and Bank Rate: the current Bank Rate.
- ECB, Key ECB interest rates: the deposit facility rate and its history.
- GOV.UK, Tax on dividends: the £500 dividend allowance.
- GOV.UK, Rent a room in your home: the £7,500 Rent a Room Scheme.
- FCA, Understanding high-risk investments: the chance of higher returns and the possible loss of all the money put in.
- Amazon KDP Help, eBook Royalties.
- Fragmenta Books, open book collections: the monthly royalty records and original KDP reports of each collection.
About Fragmenta Books
Fragmenta Books is a platform operated by Tech Go Ltd, a company registered in England and Wales (company number 14776862), founded in 2023 and based in Brentford, United Kingdom. It lets people participate in the net royalties of book collections published on Amazon KDP and Audible: each participation right is created by a legal agreement and recorded as a token on the Base blockchain; the part of the royalties that belongs to each participant is paid every quarter in USDC.
Fragmenta Books was created by three teams that joined forces: publishing entrepreneurs with more than 10 years of experience on Amazon and Audible, a team of blockchain developers with 6 years of experience in real-world asset (RWA) tokenization, and a legal team specialised in RWA tokenization worldwide.
Contact Us
- Email: info@fragmentabooks.com
- Platform: Fragmenta Books
- Company: Tech Go Ltd — company number 14776862
- Address: 24 Tax Suite 137b Westlink House, 981 Great West Road, Brentford, TW8 9DN, United Kingdom